Wilson Wu
Chief Revenue Officer, Snappy
November 11, 2026·10 min read
A British Columbia restaurant bill can carry three different tax treatments on one piece of paper. Food is exempt from PST. Liquor carries 10% PST. A mandatory gratuity carries no PST, though it does carry GST. If your POS applies one flat 12% to everything, the receipt is wrong from the first table on opening night, and most of the error lands on your guest.
The fix is simple, but it has to be done per item category, not per bill. This guide walks through what each line of a BC restaurant receipt should charge in 2026, three common setup mistakes, and a ten-minute test for your own system.
Think of your bill as a grocery bag with three kinds of things in it. Food gets a small sticker (GST only). Drinks with alcohol get a bigger sticker (GST plus 10% PST). The automatic tip is its own little pouch: it gets the GST sticker but never the PST one. A good POS puts the right sticker on each thing as it goes in the bag. A bad one slaps the same big sticker on the whole bag at the end.
PST applies to liquor and a short list of other items. It does not apply to the meal. The province sorts the bill like this (Government of British Columbia):
Bundles have their own rule. Under the province’s bundled sales bulletin (PST 316), PST generally applies only to the fair market value of the taxable portion. Its example: if you sell a meal package that includes a glass of wine, you charge 10% PST on the fair market value of the glass of wine, not on the whole package.
That matters for any set menu, banquet package or lunch special that includes a drink. The POS has to split a bundle into its taxable and exempt parts, or you end up taxing all of it or none of it.
Bring a receipt, we will check the tax lines
Pick a recent bill with food, drinks and an auto-gratuity, and we will walk through what each line should carry.
Check my receiptPST on liquor is 10% of the selling price, and it must show as its own line. The BC page allows three calculation methods depending on how you price drinks: tax-excluded pricing (10% of the pre-tax price), GST-included pricing (a factor of 9.52%), or GST- and PST-included pricing (a factor of 8.7%). In all cases you must show PST as a separate item on what you give the customer.
Most restaurants price drinks before tax, so the arithmetic is simple. A $60 liquor line carries $6.00 PST. GST is calculated on the price without the PST, as the CRA states for places where PST is charged (Canada Revenue Agency). That line carries $3.00 GST, for $69.00 in total, a combined 15%. If your menu board prices drinks tax-included, ask your accountant which factor applies and check the POS back-calculates to the same result.
A mandatory gratuity carries no PST but does carry GST. Two agencies apply two rules to the same line, which is why setups go wrong.
On PST, the province is clear: no PST on mandatory gratuities, even if the gratuity was calculated only on taxable beverage purchases (Government of British Columbia). On GST, the federal rule runs the other way. A tip freely given by a customer is not subject to GST/HST, but a mandatory or suggested amount added to the bill is (Canada Revenue Agency).
So an 18% auto-gratuity on a large party takes 5% GST and 0% PST. A tip the guest keys in on the terminal after dinner is the guest’s own choice, so it carries no tax. Your POS needs to treat those as two different things.
One caution. The BC page does not discuss voluntary tips, non-mandatory service charges, delivery fees or cover charges. If you charge any of those, confirm the treatment with the Ministry of Finance or your accountant instead of guessing.
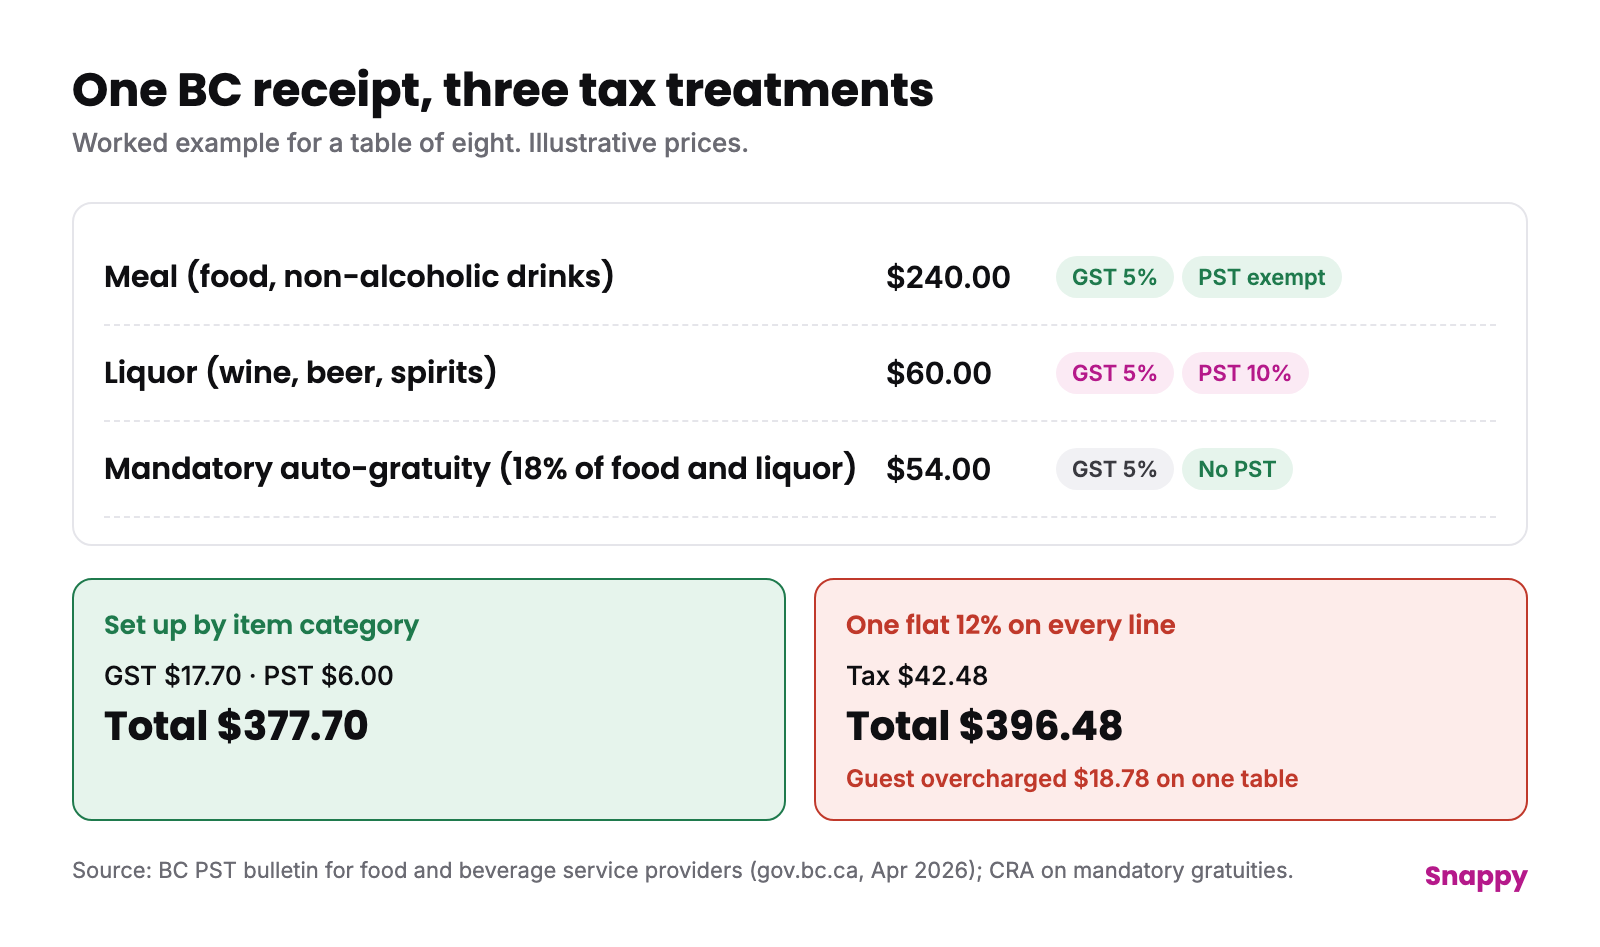
Take a table of eight with illustrative prices: a $240.00 meal, $60.00 of liquor, and a mandatory 18% auto-gratuity of $54.00 on food and liquor before tax.
| Line | Amount | GST 5% | PST | Line total |
|---|---|---|---|---|
| Meal | $240.00 | $12.00 | Exempt | $252.00 |
| Liquor | $60.00 | $3.00 | 10% = $6.00 | $69.00 |
| Auto-gratuity (mandatory) | $54.00 | $2.70 | None | $56.70 |
| Total | $354.00 | $17.70 | $6.00 | $377.70 |
Now run it through the flat 12% mistake, 5% GST plus 7% PST on every line. PST becomes $16.80 on the meal, $4.20 on the liquor and $3.78 on the gratuity, $24.78 in all against the correct $6.00. The guest pays $396.48, which is $18.78 too much. Only the liquor line comes out low: 7% PST instead of 10% is $1.80 short.
Both errors matter. Overcharging the meal is a guest-facing mistake on a receipt a diner can photograph and post. Undercharging liquor is a tax exposure that sits with you. If you think your system has been charging the wrong rate, talk to your accountant about correcting past periods before changing anything.
Three show up again and again, and each one is a configuration choice, not a tax-law puzzle.
1. A flat 12% on everything. Someone entered a single “BC tax” of 5% GST plus 7% PST on day one because it was fastest. Meals are overcharged by 7 points, liquor is undercharged by 3, and gratuities pick up PST they should never carry.
2. PST on the auto-gratuity. The service charge was built as a normal menu item and inherited the default PST rule. It needs its own tax profile: GST yes, PST no.
3. Liquor sitting in the same category as food. Cocktails, beer and wine are keyed under “Drinks” beside coffee and tea, and the category has one rate. Either the coffee gets PST or the wine does not. Liquor and non-alcoholic drinks need separate categories, with sodas checked against the 7% rule.
Package menus add a fourth: bundles that include a drink. The POS has to split out the fair market value of the liquor.
Software fees are a separate matter. The BC government’s software page says SaaS is taxable when used on an electronic device ordinarily situated in B.C., and gives a monthly subscription as an example where PST applies to the monthly fee (Government of British Columbia). Check whether your POS quote is before or after tax.
Store the tax rule on the item category, not on the bill. A “Food” category carries GST only. A “Liquor” category carries GST and 10% PST. A “Service charge” category carries GST and no PST. A guest’s tip entry carries no tax. Each item then inherits the right rule without anyone thinking about it.
This matters most in three places:
Our Vancouver team can walk through your menu categories with you during setup.
Ring five test tickets before service on a training table, compare each to a calculator, and keep the printouts.
If any ticket disagrees with your calculation, fix the category before you print another receipt.
No. The province says sales of food for human consumption are exempt, including meals, coffee and snack foods. Soda beverages are the exception, listed at 7% (Government of British Columbia).
10%, shown as a separate item on the receipt. That covers beer, ciders and coolers, mixed drinks, spirits, liqueurs, wine and any beverage over 1% alcohol.
No PST, but yes GST. The province says mandatory gratuities are not part of the purchase price, and the CRA says a mandatory or suggested amount added to a bill is subject to GST/HST (Canada Revenue Agency).
Yes. The CRA lists BC at 5% GST, and its eating-establishments policy says an establishment whose food and beverage sales are almost entirely taxable must charge GST/HST on all of them. That policy is dated December 17, 2008, so confirm it against current CRA guidance (Canada Revenue Agency).
Because someone entered one combined rate at setup. Twelve percent is 5% GST plus 7% PST, and the 7% does not apply to meals. Switch to rules by item category and run the five test tickets.
Three lines, three treatments. Meals are PST-exempt. Liquor carries 10% PST. A mandatory gratuity carries no PST but does carry 5% GST. PST must show as its own line.
The mistakes are setup mistakes. A flat 12% overcharges your guests and undercharges your liquor. PST on an auto-gratuity charges tax the province says does not apply. Each one disappears when the rule lives on the item category instead of the bill.
This is general information from the BC government and CRA pages linked here, not tax advice. Confirm your setup with your accountant or the Ministry of Finance.
Want a second pair of eyes on your tax categories before tonight’s service? Call our team at 1-855-818-0058, or book a demo and we will walk through your menu with you.
Book a walkthrough
Want a second pair of eyes on your tax setup?
Book a walkthrough and we will go through a table of eight, line by line, at BC rates.
Written by
Wilson Wu
Chief Revenue Officer, Snappy
Wilson Wu is Chief Revenue Officer at Snappy, the restaurant technology company, and is based in Boston. His first job was in a restaurant kitchen, and he has spent his career since at the intersection of hospitality and software, working with operators across Canada on the systems their service runs on. He also builds the technology he writes about. His engineering work includes a per-location customer service agent that answers guests with a restaurant's real hours, menu and prices, deployed with independent restaurants, and a document-extraction model that reads supplier invoices and matches invoice numbers against what is owed. He writes here about what changes on a busy service: ordering, payments, loyalty, the phone, and the Canadian rules behind them. He holds an MBA from Duke University and a Master of Science in Computer Science from Georgia Tech.
Connect on LinkedInNo-obligation walkthrough
Is your POS charging PST on meals?
Bring one recent receipt and we will check each line: food, liquor, gratuity and GST.
On this page
Get The Latest Restaurant Data, Trends & Tips